A Level · Accounting 9706 · Statement of cash flows (IAS 7): A Level Accounting notes and worked example
Statement of cash flows (IAS 7): A Level Accounting notes and worked example
The Daily 5 Five questions a day on A Level Accounting: two minutes, new every day, with a streak to keep Play today’s →
Opens inside this page. Prefer your own PDF app? Open the PDF.
Check yourself
5 quick questions on A Level Accounting
Tap an answer to see if you are right, and why. Free, no sign-up.
Start the free test👍 32 students found these notes useful
Was this note useful?
Full text of Statement of cash flows (IAS 7): A Level Accounting notes and worked example
These notes cover the statement of cash flows for limited companies as required for Cambridge International A Level Accounting 9706, Paper 3. They follow the syllabus order: why the statement is prepared, the IAS 7 layout, operating activities by the indirect method, investing and financing activities, the treatment of special items, and the reconciliation to cash. A fully worked example and practice questions follow at the end. All figures are in $000 unless stated otherwise.
1. Purpose and advantages of the statement of cash flows
1.1 Why profit is not the same as cash
The income statement is prepared on the accruals (matching) basis. Revenue is recorded when it is earned, not when the cash is received, and expenses are recorded when they are incurred, not when they are paid. Non-cash expenses such as depreciation reduce profit but involve no movement of cash. As a result, a company can report a healthy profit while its bank balance falls, and some profitable businesses fail because they run out of cash.
The statement of cash flows removes the effect of the accruals concept. It shows where cash came from and where it went during the period, and explains why the cash and cash equivalents balance has changed between two statements of financial position.
Statement of cash flows: a financial statement that shows the inflows and outflows of cash and cash equivalents during a period, classified into operating, investing and financing activities.
1.2 Purpose
IAS 7 Statement of Cash Flows requires companies that prepare financial statements under International Financial Reporting Standards to include a statement of cash flows. Its purpose is to give users information about the company's ability to generate cash and cash equivalents and about how it uses that cash.
1.3 Advantages to users
- Liquidity and solvency: users can judge whether the company generates enough cash from its trading to pay its debts as they fall due.
- Objectivity: cash flows are facts. They are not affected by judgements such as the choice of depreciation method or the size of an allowance for irrecoverable debts, so they are harder to manipulate than profit.
- Quality of profit: comparing profit from operations with cash generated from operations shows whether profit is being turned into cash.
- Comparability: because cash flows are not affected by different accounting policies, it is easier to compare companies.
- Funding decisions: it shows how the company financed its investment, for example by issuing shares, borrowing, or from operating cash, and whether it relies on loans.
- Future planning: past cash flows help users to predict future cash flows, dividend payments and the need for further finance.
- Stewardship: shareholders can see how directors have used the cash available, for example how much was spent on new non-current assets.
1.4 Limitations
- It is historical and does not show future cash flows.
- Cash at the year end can be "window dressed", for example by delaying payments to suppliers just before the year end.
- It does not show profitability, so it must be read alongside the income statement and statement of financial position.
2. IAS 7 definitions and layout
2.1 Key definitions
Cash: cash on hand and demand deposits.
Cash equivalents: short-term, highly liquid investments that are readily convertible to known amounts of cash and which are subject to an insignificant risk of changes in value. In practice this usually means investments with a maturity of three months or less from the date of acquisition.
Operating activities: the principal revenue-producing activities of the entity and other activities that are not investing or financing activities.
Investing activities: the acquisition and disposal of long-term assets and other investments not included in cash equivalents.
Financing activities: activities that result in changes in the size and composition of the contributed equity and borrowings of the entity.
A bank overdraft that is repayable on demand and forms part of the company's cash management is normally treated as a component of cash and cash equivalents (as a negative figure), not as financing.
2.2 The layout
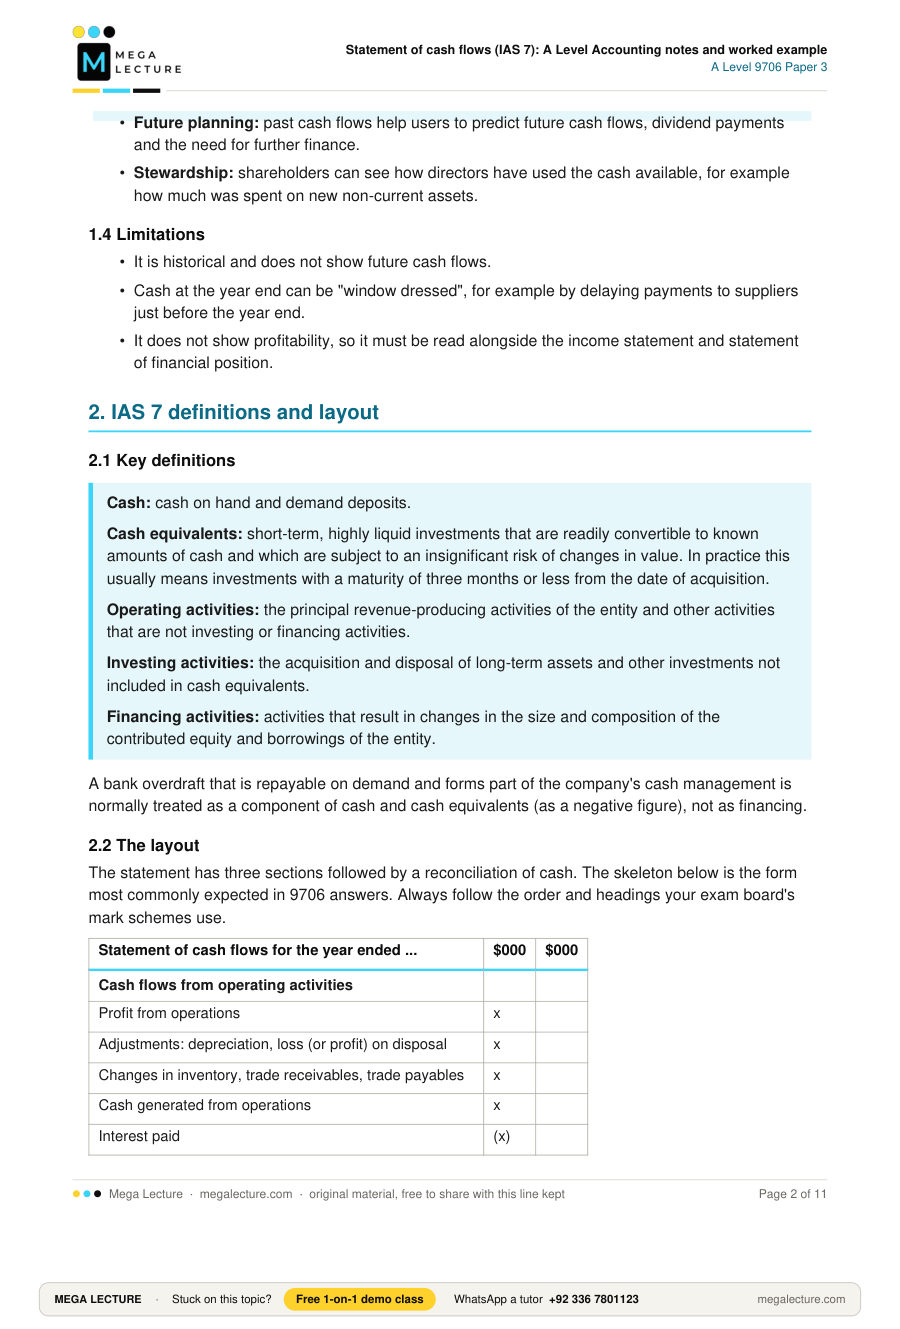
The statement has three sections followed by a reconciliation of cash. The skeleton below is the form most commonly expected in 9706 answers. Always follow the order and headings your exam board's mark schemes use.
| Statement of cash flows for the year ended ... | $000 | $000 |
|---|---|---|
| Cash flows from operating activities | ||
| Profit from operations | x | |
| Adjustments: depreciation, loss (or profit) on disposal | x | |
| Changes in inventory, trade receivables, trade payables | x | |
| Cash generated from operations | x | |
| Interest paid | (x) | |
| Tax paid | (x) | |
| Net cash from (used in) operating activities | x | |
| Cash flows from investing activities | ||
| Purchase of property, plant and equipment | (x) | |
| Proceeds from sale of property, plant and equipment | x | |
| Interest received, dividends received | x | |
| Net cash from (used in) investing activities | x | |
| Cash flows from financing activities | ||
| Proceeds from issue of shares | x | |
| Proceeds from (repayment of) debentures and loans | x | |
| Dividends paid | (x) | |
| Net cash from (used in) financing activities | x | |
| Net increase (decrease) in cash and cash equivalents | x | |
| Cash and cash equivalents at start of year | x | |
| Cash and cash equivalents at end of year | x |
2.3 Direct and indirect methods
IAS 7 allows net cash from operating activities to be shown by either method. The direct method lists actual cash receipts from customers and cash payments to suppliers and employees. The indirect method starts with profit and adjusts it for non-cash items and changes in working capital. IAS 7 encourages the direct method, but the indirect method is far more common in practice and is the method tested at this level.
3. Operating activities: the indirect method
3.1 Starting point
Start with profit from operations (operating profit), which is profit before finance costs and tax. If you are given profit for the year (after tax) or profit before tax, work back to profit from operations by adding back tax and finance costs, then deal with interest paid and tax paid separately lower down.
3.2 Adjustments for non-cash items
Some items reduce or increase profit without any cash moving. They must be reversed.
- Depreciation and amortisation: added back. They are expenses that reduce profit, but no cash leaves the business. The cash went out when the asset was bought, and that is shown under investing activities.
- Loss on disposal of non-current assets: added back. It is a book adjustment that reduced profit; the actual cash received is shown in investing activities.
- Profit on disposal of non-current assets: deducted, for the same reason.
- Increase in allowance for irrecoverable debts (if receivables are given net, this is already dealt with by the change in net receivables): a non-cash expense, so it is added back if receivables are shown gross.
Exam tip: depreciation is not a source of cash. Adding it back simply cancels out an expense that did not involve cash. Examiners reward this exact explanation.
3.3 Changes in working capital
Changes in inventory, trade receivables and trade payables explain the timing difference between profit and cash.
| Item | Increase during year | Decrease during year | Reason |
|---|---|---|---|
| Inventory | Deduct | Add | More cash tied up in goods that have not yet been sold |
| Trade receivables | Deduct | Add | Sales recorded in profit but cash not yet received |
| Trade payables | Add | Deduct | Purchases recorded but cash not yet paid, so cash is retained |
| Prepayments of expenses | Deduct | Add | Cash paid in advance of the expense |
| Accruals of expenses (not interest or tax) | Add | Deduct | Expense recorded but not yet paid |
A simple rule: an increase in a current asset uses cash (deduct); an increase in a current liability saves cash (add). Do not include cash, tax payable, interest accrued or dividends payable in the working capital adjustments, because these are dealt with elsewhere.
3.4 Cash generated from operations, interest and tax
After the adjustments you reach cash generated from operations. Interest paid and tax paid are then deducted to give net cash from operating activities. The amounts actually paid are rarely the same as the charges in the income statement, so you usually need a workings account (section 5).
4. Investing and financing activities
4.1 Investing activities
Investing activities show cash spent on, and received from, long-term assets and investments:
- purchase of property, plant and equipment (outflow);
- purchase of intangible assets and long-term investments (outflow);
- proceeds from the sale of non-current assets (inflow);
- interest received and dividends received (inflows, if the company classifies them here).
The purchase figure is often not given. You calculate it from the opening and closing balances, depreciation and disposals (see the worked example).
4.2 Financing activities
Financing activities show cash from, and repayments to, the providers of long-term finance:
- proceeds from issuing ordinary or preference shares, including any premium (inflow);
- proceeds from issuing debentures or taking out long-term loans (inflow);
- repayment of debentures or loans and redemption of shares (outflow);
- dividends paid (outflow).
Exam tip: a bonus issue involves no cash. It moves reserves into share capital, so it does not appear in the statement of cash flows. When share capital rises, check whether part of the increase was a bonus issue before you record cash from a share issue. A revaluation of non-current assets is also a non-cash movement and must be removed when calculating purchases.
5. Treatment of disposals, interest, tax and dividends
5.1 Disposals of non-current assets
A disposal affects two parts of the statement:
- In operating activities, the profit on disposal is deducted from profit from operations, or the loss is added back.
- In investing activities, the cash proceeds are shown as an inflow.
Proceeds = carrying amount of the asset sold + profit on disposal (or − loss on disposal).
When assets are given at cost with separate accumulated depreciation, use T-accounts or the following relationships:
- Additions at cost = closing cost − opening cost + cost of assets disposed of
- Depreciation charge = closing accumulated depreciation − opening accumulated depreciation + accumulated depreciation on assets disposed of
- Carrying amount disposed of = cost of asset disposed of − its accumulated depreciation
When assets are given at carrying amount only:
- Additions = closing carrying amount − opening carrying amount + depreciation for the year + carrying amount of disposals (less any revaluation surplus)
5.2 Interest
Interest paid = opening interest accrued + finance cost in income statement − closing interest accrued.
IAS 7 allows interest paid to be classified as operating or financing, and interest received as operating or investing, as long as the choice is applied consistently. In 9706 answers interest paid is commonly shown in operating activities after cash generated from operations, and interest received in investing activities.
5.3 Tax
Tax paid = opening tax liability + tax charge in income statement − closing tax liability.
Tax paid is classified as an operating activity unless it can be specifically identified with investing or financing activities.
5.4 Dividends
Dividends paid during the year are usually found in the statement of changes in equity. If not given, calculate them from retained earnings:
Dividends paid = opening retained earnings + profit for the year − closing retained earnings (adjusted for any other transfers, such as a transfer to general reserve or a bonus issue made from retained earnings).
Under IAS 7, dividends proposed after the year end are not a liability and are not shown as paid. Dividends paid are normally shown in financing activities (IAS 7 also permits operating). Dividends received from investments are shown in investing (or operating) activities.
Worked example: calculating tax paid
Tax payable was $30 000 at the start of the year and $36 000 at the end. The income statement tax charge was $40 000.
Tax paid = 30 000 + 40 000 − 36 000 = $34 000
Logic: the company owed $30 000 at the start, incurred another $40 000, and still owes $36 000, so it must have paid $34 000.
6. Reconciliation to cash and cash equivalents
The final part of the statement adds the net increase or decrease in cash and cash equivalents to the opening balance. The result must equal the closing balance in the statement of financial position. This is the check that your statement is complete.
If cash and cash equivalents include several items (for example cash at bank, short-term deposits and an overdraft), show them in a note:
| Analysis of cash and cash equivalents | At start $000 | At end $000 |
|---|---|---|
| Cash at bank and in hand | x | x |
| Short-term deposits (three months or less) | x | x |
| Bank overdraft | (x) | (x) |
| Total | x | x |
Exam tip: if your net change does not reconcile, check the common errors: depreciation not added back, signs reversed on working capital, charges used instead of amounts paid, the whole share issue missing its premium, a bonus issue treated as cash, or the disposal profit or loss shown as the cash proceeds.
7. Fully worked example
Worked example: Rawalpindi Fabrics plc
The statements of financial position of Rawalpindi Fabrics plc at 31 December are shown below.
| 2026 $000 | 2025 $000 | |
|---|---|---|
| Property, plant and equipment (carrying amount) | 1 450 | 1 200 |
| Inventory | 210 | 180 |
| Trade receivables | 135 | 150 |
| Cash and cash equivalents | 31 | 120 |
| Total assets | 1 826 | 1 650 |
| Ordinary shares of $1 each | 600 | 500 |
| Share premium | 80 | 50 |
| Retained earnings | 785 | 660 |
| 10% debentures | 200 | 300 |
| Trade payables | 125 | 110 |
| Tax payable | 36 | 30 |
| Total equity and liabilities | 1 826 | 1 650 |
Additional information for the year ended 31 December 2026:
- Profit from operations was $260 000. Finance costs were $25 000, all paid during the year. The tax charge was $40 000. Profit for the year was $195 000.
- Depreciation of $120 000 was charged.
- Machinery with a carrying amount of $45 000 was sold for $38 000 cash.
- 100 000 ordinary shares were issued for cash at $1.30 each.
- $100 000 of debentures were repaid at par.
- Ordinary dividends were paid during the year.
Required: prepare the statement of cash flows for the year ended 31 December 2026 in accordance with IAS 7.
Workings
W1 Loss on disposal = carrying amount 45 − proceeds 38 = 7 (added back).
W2 Purchases of PPE: opening 1 200 − depreciation 120 − disposal 45 + additions = closing 1 450, so additions = 1 450 − 1 200 + 120 + 45 = 415.
W3 Tax paid = 30 + 40 − 36 = 34.
W4 Share issue = 100 000 × $1.30 = $130 000 (share capital +100, share premium +30).
W5 Dividends paid = opening retained earnings 660 + profit for the year 195 − closing retained earnings 785 = 70.
W6 Working capital: inventory up 30 (deduct); receivables down 15 (add); payables up 15 (add).
| Rawalpindi Fabrics plc: statement of cash flows for the year ended 31 December 2026 | $000 | $000 |
|---|---|---|
| Cash flows from operating activities | ||
| Profit from operations | 260 | |
| Depreciation | 120 | |
| Loss on disposal (W1) | 7 | |
| Increase in inventory | (30) | |
| Decrease in trade receivables | 15 | |
| Increase in trade payables | 15 | |
| Cash generated from operations | 387 | |
| Interest paid | (25) | |
| Tax paid (W3) | (34) | |
| Net cash from operating activities | 328 | |
| Cash flows from investing activities | ||
| Purchase of property, plant and equipment (W2) | (415) | |
| Proceeds from sale of machinery | 38 | |
| Net cash used in investing activities | (377) | |
| Cash flows from financing activities | ||
| Proceeds from issue of ordinary shares (W4) | 130 | |
| Repayment of debentures | (100) | |
| Dividends paid (W5) | (70) | |
| Net cash used in financing activities | (40) | |
| Net decrease in cash and cash equivalents | (89) | |
| Cash and cash equivalents at 1 January 2026 | 120 | |
| Cash and cash equivalents at 31 December 2026 | 31 |
Check: 328 − 377 − 40 = −89; 120 − 89 = 31, which agrees with the closing statement of financial position.
Comment: the company generated $328 000 from operations, more than its profit for the year, mainly because depreciation is a large non-cash expense. Operating cash was not enough to fund $415 000 of new equipment, and the share issue was largely used to repay debentures, so cash fell by $89 000.
Quick check
Questions 1 to 8 are short exam-style questions. Questions 9 and 10 are practice questions in the style of Paper 3.
- State the purpose of a statement of cash flows. [2]
- Explain two advantages to a shareholder of a statement of cash flows compared with an income statement. [4]
- Explain why depreciation is added to profit from operations when using the indirect method. [2]
- State in which section of the statement of cash flows each of the following appears: (a) purchase of a delivery vehicle, (b) dividends paid, (c) tax paid, (d) proceeds from an issue of debentures. [4]
- Explain why an increase in trade receivables is deducted in the operating activities section. [2]
- A company reported a profit for the year but its bank balance fell. Suggest three possible reasons. [3]
- Tax payable was $42 000 at the start of the year and $47 000 at the end. The tax charge was $55 000. Calculate the tax paid during the year. [2]
- A machine that cost $60 000, with accumulated depreciation of $41 000, was sold at a profit of $4 000. Calculate the cash proceeds and state how the sale is shown in the statement of cash flows. [4]
- Practice question 1. The following information relates to Mardan Traders Ltd for the year ended 30 June 2026 ($000): profit from operations 180; depreciation 64; profit on disposal of equipment 9; inventory decreased by 12; trade receivables increased by 20; trade payables decreased by 8; finance costs 18, with interest accrued of 4 at the start of the year and 6 at the end; tax charge 30, with tax payable of 25 at the start and 28 at the end. Prepare the operating activities section of the statement of cash flows. [8]
- Practice question 2. Extracts for Quetta Engineering plc at 31 March ($000):
During the year plant that cost 70, with accumulated depreciation of 50, was sold for 15 cash. All shares were issued for cash. Profit for the year was 170, and there were no transfers to other reserves. (a) Calculate the depreciation charge and the profit or loss on disposal. (b) Prepare the investing and financing sections of the statement of cash flows. [10]2026 2025 Plant at cost 950 800 Accumulated depreciation on plant 290 240 Ordinary shares of $1 each 500 400 Share premium 90 60 8% debentures 150 0 Retained earnings 410 300
1. To show the inflows and outflows of cash and cash equivalents during the period, classified into operating, investing and financing activities (1), so that users can assess the company's ability to generate cash and how it uses that cash (1).
2. Any two, each explained (2 marks each):
Cash flows are objective: they are not affected by accounting judgements such as depreciation methods, so they are harder to manipulate than profit.
It shows liquidity: the shareholder can see whether the company generates enough cash to pay its debts and to pay dividends, which the income statement does not show.
It shows how investment was financed, for example by borrowing or share issues, so the shareholder can judge financial risk.
Comparing profit from operations with cash generated from operations shows the quality of profit.
3. Depreciation is a non-cash expense: it reduced profit but no cash left the business in the year (1). Adding it back removes its effect so that the figure reflects cash flows; the cash outflow was recorded when the asset was bought, under investing activities (1).
4. (a) Investing activities. (b) Financing activities. (c) Operating activities. (d) Financing activities. (1 each)
5. Revenue included in profit has not all been received in cash (1); the increase represents sales for which cash is still owed by customers, so cash inflow is lower than revenue and the increase must be deducted (1).
6. Any three (1 each): large purchases of non-current assets; repayment of loans or debentures; payment of dividends; increase in inventory or trade receivables; decrease in trade payables; large tax or interest payments; redemption of shares.
7. Tax paid = opening liability + charge − closing liability (1) = 42 000 + 55 000 − 47 000 = $50 000 (1).
8. Carrying amount = 60 000 − 41 000 = $19 000 (1). Proceeds = 19 000 + 4 000 = $23 000 (1). The profit on disposal of $4 000 is deducted from profit from operations in operating activities (1). The proceeds of $23 000 are shown as an inflow in investing activities (1).
9. Practice question 1
Workings: interest paid = 4 + 18 − 6 = 16. Tax paid = 25 + 30 − 28 = 27.
| Mardan Traders Ltd: cash flows from operating activities, year ended 30 June 2026 | $000 |
|---|---|
| Profit from operations | 180 |
| Depreciation | 64 |
| Profit on disposal of equipment | (9) |
| Decrease in inventory | 12 |
| Increase in trade receivables | (20) |
| Decrease in trade payables | (8) |
| Cash generated from operations | 219 |
| Interest paid | (16) |
| Tax paid | (27) |
| Net cash from operating activities | 176 |
Check: 180 + 64 − 9 + 12 − 20 − 8 = 219; 219 − 16 − 27 = 176.
10. Practice question 2
(a) Depreciation charge = closing accumulated depreciation − opening + accumulated depreciation on disposal = 290 − 240 + 50 = 100.
Carrying amount of plant sold = 70 − 50 = 20. Proceeds 15, so loss on disposal = 20 − 15 = 5.
(b) Workings:
Purchases of plant = closing cost − opening cost + cost of disposals = 950 − 800 + 70 = 220.
Share issue proceeds = increase in share capital + increase in share premium = (500 − 400) + (90 − 60) = 130.
Debentures issued = 150 − 0 = 150.
Dividends paid = opening retained earnings + profit − closing retained earnings = 300 + 170 − 410 = 60.
| Quetta Engineering plc: extracts from the statement of cash flows, year ended 31 March 2026 | $000 | $000 |
|---|---|---|
| Cash flows from investing activities | ||
| Purchase of plant | (220) | |
| Proceeds from sale of plant | 15 | |
| Net cash used in investing activities | (205) | |
| Cash flows from financing activities | ||
| Proceeds from issue of ordinary shares | 130 | |
| Proceeds from issue of 8% debentures | 150 | |
| Dividends paid | (60) | |
| Net cash from financing activities | 220 |
Note: the depreciation of 100 and the loss on disposal of 5 would both be added back in the operating activities section, not shown here.
