A Level · Accounting 9706 · Manufacturing accounts: A Level Accounting notes and worked example
Manufacturing accounts: A Level Accounting notes and worked example
Opens inside this page. Prefer your own PDF app? Open the PDF.
Check yourself
5 quick questions on A Level Accounting
Tap an answer to see if you are right, and why. Free, no sign-up.
Start the free test19 of 21 students found these notes useful
Was this note useful?
Full text of Manufacturing accounts: A Level Accounting notes and worked example
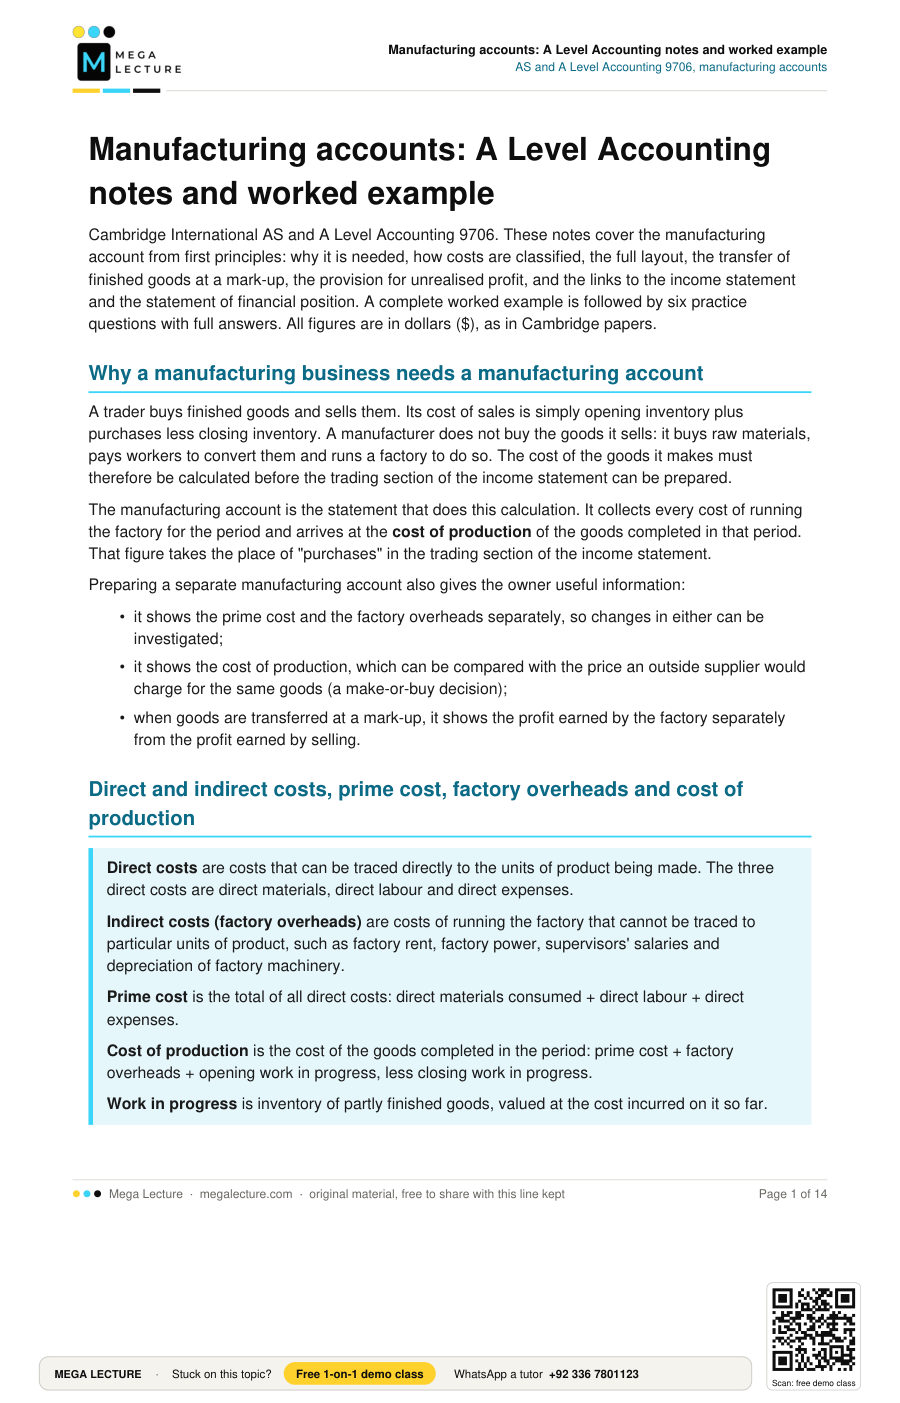
Cambridge International AS and A Level Accounting 9706. These notes cover the manufacturing account from first principles: why it is needed, how costs are classified, the full layout, the transfer of finished goods at a mark-up, the provision for unrealised profit, and the links to the income statement and the statement of financial position. A complete worked example is followed by six practice questions with full answers. All figures are in dollars ($), as in Cambridge papers.
Why a manufacturing business needs a manufacturing account
A trader buys finished goods and sells them. Its cost of sales is simply opening inventory plus purchases less closing inventory. A manufacturer does not buy the goods it sells: it buys raw materials, pays workers to convert them and runs a factory to do so. The cost of the goods it makes must therefore be calculated before the trading section of the income statement can be prepared.
The manufacturing account is the statement that does this calculation. It collects every cost of running the factory for the period and arrives at the cost of production of the goods completed in that period. That figure takes the place of "purchases" in the trading section of the income statement.
Preparing a separate manufacturing account also gives the owner useful information:
- it shows the prime cost and the factory overheads separately, so changes in either can be investigated;
- it shows the cost of production, which can be compared with the price an outside supplier would charge for the same goods (a make-or-buy decision);
- when goods are transferred at a mark-up, it shows the profit earned by the factory separately from the profit earned by selling.
Direct and indirect costs, prime cost, factory overheads and cost of production
Direct costs are costs that can be traced directly to the units of product being made. The three direct costs are direct materials, direct labour and direct expenses.
Indirect costs (factory overheads) are costs of running the factory that cannot be traced to particular units of product, such as factory rent, factory power, supervisors' salaries and depreciation of factory machinery.
Prime cost is the total of all direct costs: direct materials consumed + direct labour + direct expenses.
Cost of production is the cost of the goods completed in the period: prime cost + factory overheads + opening work in progress, less closing work in progress.
Work in progress is inventory of partly finished goods, valued at the cost incurred on it so far.
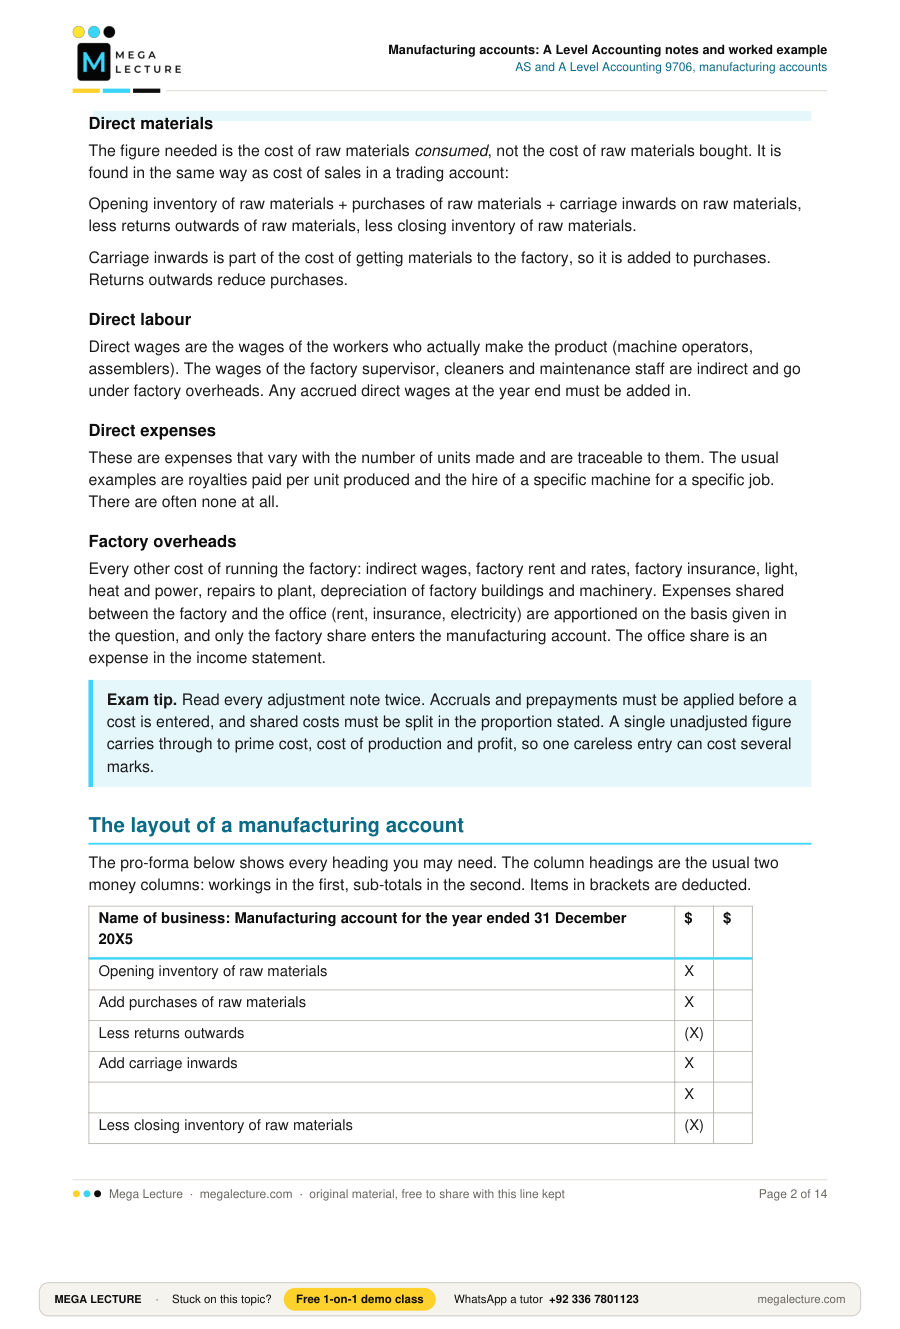
Direct materials
The figure needed is the cost of raw materials consumed, not the cost of raw materials bought. It is found in the same way as cost of sales in a trading account:
Opening inventory of raw materials + purchases of raw materials + carriage inwards on raw materials, less returns outwards of raw materials, less closing inventory of raw materials.
Carriage inwards is part of the cost of getting materials to the factory, so it is added to purchases. Returns outwards reduce purchases.
Direct labour
Direct wages are the wages of the workers who actually make the product (machine operators, assemblers). The wages of the factory supervisor, cleaners and maintenance staff are indirect and go under factory overheads. Any accrued direct wages at the year end must be added in.
Direct expenses
These are expenses that vary with the number of units made and are traceable to them. The usual examples are royalties paid per unit produced and the hire of a specific machine for a specific job. There are often none at all.
Factory overheads
Every other cost of running the factory: indirect wages, factory rent and rates, factory insurance, light, heat and power, repairs to plant, depreciation of factory buildings and machinery. Expenses shared between the factory and the office (rent, insurance, electricity) are apportioned on the basis given in the question, and only the factory share enters the manufacturing account. The office share is an expense in the income statement.
Exam tip. Read every adjustment note twice. Accruals and prepayments must be applied before a cost is entered, and shared costs must be split in the proportion stated. A single unadjusted figure carries through to prime cost, cost of production and profit, so one careless entry can cost several marks.
The layout of a manufacturing account
The pro-forma below shows every heading you may need. The column headings are the usual two money columns: workings in the first, sub-totals in the second. Items in brackets are deducted.
| Name of business: Manufacturing account for the year ended 31 December 20X5 | $ | $ |
|---|---|---|
| Opening inventory of raw materials | X | |
| Add purchases of raw materials | X | |
| Less returns outwards | (X) | |
| Add carriage inwards | X | |
| X | ||
| Less closing inventory of raw materials | (X) | |
| Cost of raw materials consumed | X | |
| Direct wages | X | |
| Direct expenses (for example royalties) | X | |
| Prime cost | X | |
| Factory overheads: | ||
| Indirect wages | X | |
| Factory rent and rates | X | |
| Factory light, heat and power | X | |
| Factory insurance | X | |
| Depreciation of factory machinery | X | |
| Total factory overheads | X | |
| X | ||
| Add opening work in progress | X | |
| Less closing work in progress | (X) | |
| Cost of production (transferred to the income statement) | X | |
| Manufacturing profit (mark-up on cost of production, if any) | X | |
| Transfer price of finished goods | X |
Two points about work in progress. First, goods that were partly made at the start of the year are completed during the year, so their opening value is added to this year's costs. Second, goods still partly made at the end of the year have not been completed, so their closing value is deducted. The result is the cost of goods actually completed in the year. If a question gives no work in progress figures, the cost of production is simply prime cost plus factory overheads.
Notice that finished goods inventory never appears in the manufacturing account. Opening and closing finished goods belong to the trading section of the income statement, exactly as the inventory of a trader does.
Transfer at cost plus a mark-up and the provision for unrealised profit
Manufacturing profit
Some businesses transfer finished goods from the factory to the trading section at cost of production plus a percentage mark-up, rather than at cost. The mark-up is the manufacturing profit. The idea is to charge the selling side of the business what it would have paid an outside supplier, so that the profit of the factory and the profit of the sales function can each be judged on its own.
In the manufacturing account the manufacturing profit is added below cost of production and the total is labelled transfer price. In the income statement the transfer price (not the cost of production) takes the place of purchases in the trading section, and the manufacturing profit is then added to gross profit in the profit and loss section. The total profit of the business is not changed by this; it is simply split into two parts.
Journal entries for the transfer (manufacturing profit of $P, cost of production $C, transfer price $C + $P)
Dr Income statement (trading section) $C + $P
Cr Manufacturing account $C + $P
Transfer of finished goods at transfer price.
Dr Manufacturing account $P
Cr Income statement (profit and loss section) $P
Manufacturing profit for the year.
Why a provision for unrealised profit is needed
When goods are transferred at a mark-up, the closing inventory of finished goods is valued at transfer price, which includes manufacturing profit. That profit has not been realised, because the goods have not been sold to an outside customer. Inventory must be valued at the lower of cost and net realisable value, so the profit element in closing finished goods must be removed before the statement of financial position is prepared. This is done by creating a provision for unrealised profit.
Provision for unrealised profit is the amount of manufacturing profit included in the closing inventory of finished goods that are valued at transfer price. It is deducted from the inventory of finished goods in the statement of financial position so that inventory is shown at cost.
Calculation: if goods are transferred at cost plus m%, the profit in inventory valued at transfer price V is V × m / (100 + m).
So at a mark-up of 20%, the provision is V × 20/120, which is one sixth of the transfer value. At 25% it is V × 25/125, one fifth. At 50% it is V × 50/150, one third.
The provision is a credit balance that is carried forward, like a provision for doubtful debts. Only the change in the provision goes through the income statement each year:
- an increase in the provision is deducted from profit (it is treated like an expense);
- a decrease in the provision is added to profit (it is treated like other income).
Journal entries for the provision
Year the provision is first created, or any year it increases:
Dr Income statement (amount of the provision, or of the increase)
Cr Provision for unrealised profit
Any year the provision decreases:
Dr Provision for unrealised profit (amount of the decrease)
Cr Income statement
How the manufacturing account links to the income statement and the statement of financial position
Income statement, trading section. Cost of sales = opening inventory of finished goods + cost of production (or transfer price, if a mark-up is used), less closing inventory of finished goods. Revenue less cost of sales gives gross profit.
Income statement, profit and loss section. Manufacturing profit (if any) is added to gross profit. An increase in the provision for unrealised profit is deducted; a decrease is added. Then all non-factory expenses are deducted: office salaries, the office share of rent, insurance and power, distribution and selling costs, depreciation of office equipment and delivery vehicles, finance costs. The result is profit for the year.
Statement of financial position. Inventory under current assets is shown in three parts: raw materials, work in progress, and finished goods. Where finished goods are valued at transfer price, the provision for unrealised profit is deducted from them so that the finished goods are shown at cost. Accrued factory expenses appear under current liabilities and prepaid factory expenses under current assets, just as for any other expense.
Worked example
Hira Furniture is a small manufacturer. The following balances were taken from the books on 31 December 2025.
| Item | $ |
|---|---|
| Inventory at 1 January 2025: raw materials | 18,000 |
| Inventory at 1 January 2025: work in progress | 9,000 |
| Inventory at 1 January 2025: finished goods (at transfer price) | 36,000 |
| Purchases of raw materials | 164,000 |
| Returns outwards of raw materials | 4,000 |
| Carriage inwards | 6,000 |
| Direct wages | 96,000 |
| Royalties (direct expense) | 5,000 |
| Factory indirect wages | 31,000 |
| Rent and rates | 30,000 |
| Factory power | 13,500 |
| Factory insurance (paid) | 4,000 |
| Revenue | 540,000 |
| Office salaries | 48,000 |
| Selling expenses | 22,000 |
| Provision for unrealised profit at 1 January 2025 | 6,000 |
Additional information:
- Inventory at 31 December 2025: raw materials $21,000; work in progress $8,000; finished goods (at transfer price) $42,000.
- Rent and rates are to be apportioned 80% to the factory and 20% to the office.
- Factory insurance of $500 was owing at 31 December 2025.
- Factory machinery is to be depreciated by $12,000 for the year.
- Finished goods are transferred to the trading section at cost of production plus 20%.
Step 1: apply the adjustments
Factory rent and rates = 30,000 × 80% = 24,000. Office rent and rates = 30,000 × 20% = 6,000. Check: 24,000 + 6,000 = 30,000.
Factory insurance for the year = 4,000 paid + 500 owing = 4,500. The $500 accrual is a current liability.
Depreciation of factory machinery = 12,000 (given), a factory overhead.
Step 2: manufacturing account
| Hira Furniture: Manufacturing account for the year ended 31 December 2025 | $ | $ |
|---|---|---|
| Opening inventory of raw materials | 18,000 | |
| Add purchases of raw materials | 164,000 | |
| Less returns outwards | (4,000) | |
| Add carriage inwards | 6,000 | |
| 184,000 | ||
| Less closing inventory of raw materials | (21,000) | |
| Cost of raw materials consumed | 163,000 | |
| Direct wages | 96,000 | |
| Royalties | 5,000 | |
| Prime cost | 264,000 | |
| Factory overheads: | ||
| Indirect wages | 31,000 | |
| Rent and rates (80%) | 24,000 | |
| Power | 13,500 | |
| Insurance (4,000 + 500) | 4,500 | |
| Depreciation of machinery | 12,000 | |
| Total factory overheads | 85,000 | |
| 349,000 | ||
| Add opening work in progress | 9,000 | |
| 358,000 | ||
| Less closing work in progress | (8,000) | |
| Cost of production | 350,000 | |
| Manufacturing profit (350,000 × 20%) | 70,000 | |
| Transfer price of finished goods | 420,000 |
Arithmetic checks: 18,000 + 164,000 = 182,000; 182,000 − 4,000 = 178,000; 178,000 + 6,000 = 184,000; 184,000 − 21,000 = 163,000. Prime cost: 163,000 + 96,000 + 5,000 = 264,000. Overheads: 31,000 + 24,000 + 13,500 + 4,500 + 12,000 = 85,000. 264,000 + 85,000 = 349,000; + 9,000 = 358,000; − 8,000 = 350,000. Mark-up: 350,000 × 20/100 = 70,000; 350,000 + 70,000 = 420,000.
Step 3: income statement
| Hira Furniture: Income statement for the year ended 31 December 2025 | $ | $ |
|---|---|---|
| Revenue | 540,000 | |
| Opening inventory of finished goods | 36,000 | |
| Add transfer price of finished goods | 420,000 | |
| 456,000 | ||
| Less closing inventory of finished goods | (42,000) | |
| Cost of sales | (414,000) | |
| Gross profit | 126,000 | |
| Add manufacturing profit | 70,000 | |
| 196,000 | ||
| Less increase in provision for unrealised profit | (1,000) | |
| 195,000 | ||
| Less expenses: | ||
| Office salaries | 48,000 | |
| Rent and rates (20%) | 6,000 | |
| Selling expenses | 22,000 | |
| Total expenses | (76,000) | |
| Profit for the year | 119,000 |
Arithmetic checks: 36,000 + 420,000 = 456,000; 456,000 − 42,000 = 414,000; 540,000 − 414,000 = 126,000; 126,000 + 70,000 = 196,000; 196,000 − 1,000 = 195,000; 48,000 + 6,000 + 22,000 = 76,000; 195,000 − 76,000 = 119,000.
Step 4: the provision for unrealised profit
Mark-up is 20%, so profit in inventory = transfer value × 20/120.
Provision needed at 31 December 2025 = 42,000 × 20/120 = 7,000.
Provision at 1 January 2025 = 6,000 (check: 36,000 × 20/120 = 6,000).
Increase in provision = 7,000 − 6,000 = 1,000. This is the figure deducted in the income statement above.
Journal entry: Dr Income statement 1,000; Cr Provision for unrealised profit 1,000.
Provision for unrealised profit account: balance b/d 6,000 Cr; income statement 1,000 Cr; balance c/d 7,000 on the debit side to close the account, brought down as a credit balance of 7,000.
Step 5: statement of financial position extract at 31 December 2025
| Current assets | $ | $ |
|---|---|---|
| Inventory: raw materials | 21,000 | |
| Inventory: work in progress | 8,000 | |
| Inventory: finished goods at transfer price | 42,000 | |
| Less provision for unrealised profit | (7,000) | 35,000 |
| Total inventory | 64,000 | |
| Current liabilities | ||
| Accrued factory insurance | 500 |
Check: 42,000 − 7,000 = 35,000, and 35,000 is the cost of the finished goods (35,000 × 120/100 = 42,000). Total inventory: 21,000 + 8,000 + 35,000 = 64,000.
Key terms
| Term | Meaning |
|---|---|
| Manufacturing account | Statement that calculates the cost of production of goods completed in a period. |
| Direct materials | Raw materials that become part of the product; charged at the cost consumed, not the cost bought. |
| Direct labour | Wages of workers who make the product. |
| Direct expenses | Expenses traceable to units made, such as royalties per unit. |
| Prime cost | Total of direct materials, direct labour and direct expenses. |
| Factory overheads | Indirect costs of running the factory. |
| Apportionment | Splitting a shared cost between factory and office on a stated basis. |
| Work in progress | Partly finished goods, valued at cost incurred so far. |
| Cost of production | Prime cost + factory overheads + opening WIP, less closing WIP. |
| Transfer price | Cost of production plus manufacturing profit, the value at which finished goods pass to the trading section. |
| Manufacturing profit | The mark-up added to cost of production; credited to the profit and loss section. |
| Provision for unrealised profit | The manufacturing profit contained in closing finished goods inventory; deducted from inventory in the statement of financial position. |
| Unrealised profit | Profit recorded on goods that have not yet been sold to an outside customer. |
| Carriage inwards | Cost of transporting purchases to the business; added to purchases of raw materials. |
| Returns outwards | Raw materials sent back to suppliers; deducted from purchases. |
| Cost of sales | Opening finished goods + cost of production (or transfer price), less closing finished goods. |
| Gross profit | Revenue less cost of sales. |
| Make-or-buy decision | Comparing the cost of production per unit with an outside supplier's price. |
Practice
Saleem Ceramics makes pottery. The following information is available for the year ended 30 June 2026.
Item $ Inventory of raw materials at 1 July 2025 12,400 Inventory of raw materials at 30 June 2026 14,100 Work in progress at 1 July 2025 5,800 Work in progress at 30 June 2026 6,300 Purchases of raw materials 98,600 Carriage inwards 2,300 Direct wages 57,200 Direct expenses 3,100 Factory indirect wages 18,900 Factory rent 15,000 Factory light and heat 6,400 Depreciation of factory plant 9,000 Factory supervisor's salary 21,500 Prepare the manufacturing account for the year ended 30 June 2026, showing clearly the cost of raw materials consumed, prime cost, total factory overheads and cost of production. [12]
Nadia Textiles manufactures bed linen and transfers finished goods to the trading section at cost of production plus 25%. The following balances were extracted at 31 March 2026.
Item $ Inventory at 1 April 2025: raw materials 27,500 Inventory at 1 April 2025: work in progress 11,200 Inventory at 1 April 2025: finished goods (at transfer price) 40,800 Purchases of raw materials 213,400 Returns outwards of raw materials 3,400 Carriage inwards 5,600 Direct wages 118,000 Royalties 7,500 Factory indirect wages 42,300 Rent and rates 36,000 Factory power 19,700 Insurance 9,600 Factory machinery at cost 150,000 Office equipment at cost 20,000 Revenue 620,000 Office salaries 58,000 Distribution costs 27,900 Provision for unrealised profit at 1 April 2025 8,160 Additional information at 31 March 2026:
- Inventory: raw materials $25,900; work in progress $13,300; finished goods at transfer price $46,800.
- Direct wages of $2,000 were accrued.
- Rent and rates of $4,000 were prepaid. Rent and rates are apportioned three quarters to the factory and one quarter to the office.
- Insurance is apportioned two thirds to the factory and one third to the office.
- Factory machinery and office equipment are both depreciated at 10% per annum on cost.
(a) Prepare the manufacturing account for the year ended 31 March 2026. [14]
(b) Prepare the income statement for the year ended 31 March 2026. [10]
(c) Calculate the total value of inventory to be shown in the statement of financial position at 31 March 2026. [3]Imran Engineering transfers finished goods to its trading section at cost plus 20%. Finished goods inventory valued at transfer price was $33,600 on 1 January 2025 and $28,800 on 31 December 2025.
(a) Calculate the provision for unrealised profit required at 1 January 2025 and at 31 December 2025. [4]
(b) Prepare the journal entry to record the change in the provision for the year ended 31 December 2025. A narrative is not required. [3]
(c) State the value at which finished goods inventory will appear in the statement of financial position at 31 December 2025. [2]
(d) Explain why a provision for unrealised profit is required. [3]State two differences between direct costs and factory overheads, and give one example of each type of cost. [4]
Explain how opening and closing work in progress are treated in the manufacturing account and why. [4]
Kamran manufactures 15,000 identical units a year. In the year just ended his prime cost was $184,000 and his factory overheads were $61,000, of which $38,000 was depreciation of machinery and factory rent. Work in progress was $9,500 at the start of the year and $10,000 at the end. A supplier has offered to sell him the same units for $16.00 each.
(a) Calculate the cost of production and the cost of production per unit. [4]
(b) Evaluate whether Kamran should accept the supplier's offer. [6]
Answer 1
| Saleem Ceramics: Manufacturing account for the year ended 30 June 2026 | $ | $ |
|---|---|---|
| Opening inventory of raw materials | 12,400 | |
| Add purchases of raw materials | 98,600 | |
| Add carriage inwards | 2,300 | |
| 113,300 | ||
| Less closing inventory of raw materials | (14,100) | |
| Cost of raw materials consumed | 99,200 | |
| Direct wages | 57,200 | |
| Direct expenses | 3,100 | |
| Prime cost | 159,500 | |
| Factory overheads: | ||
| Indirect wages | 18,900 | |
| Rent | 15,000 | |
| Light and heat | 6,400 | |
| Depreciation of plant | 9,000 | |
| Supervisor's salary | 21,500 | |
| Total factory overheads | 70,800 | |
| 230,300 | ||
| Add opening work in progress | 5,800 | |
| 236,100 | ||
| Less closing work in progress | (6,300) | |
| Cost of production | 229,800 |
Workings: 12,400 + 98,600 + 2,300 = 113,300; 113,300 − 14,100 = 99,200. Prime cost 99,200 + 57,200 + 3,100 = 159,500. Overheads 18,900 + 15,000 + 6,400 + 9,000 + 21,500 = 70,800. 159,500 + 70,800 = 230,300; + 5,800 = 236,100; − 6,300 = 229,800.
Answer 2
Adjustments first. Direct wages = 118,000 + 2,000 accrued = 120,000. Rent and rates for the year = 36,000 − 4,000 prepaid = 32,000; factory 3/4 = 24,000, office 1/4 = 8,000 (check 24,000 + 8,000 = 32,000). Insurance: factory 2/3 × 9,600 = 6,400, office 1/3 × 9,600 = 3,200 (check 6,400 + 3,200 = 9,600). Depreciation: factory machinery 150,000 × 10% = 15,000; office equipment 20,000 × 10% = 2,000.
(a)
| Nadia Textiles: Manufacturing account for the year ended 31 March 2026 | $ | $ |
|---|---|---|
| Opening inventory of raw materials | 27,500 | |
| Add purchases of raw materials | 213,400 | |
| Less returns outwards | (3,400) | |
| Add carriage inwards | 5,600 | |
| 243,100 | ||
| Less closing inventory of raw materials | (25,900) | |
| Cost of raw materials consumed | 217,200 | |
| Direct wages (118,000 + 2,000) | 120,000 | |
| Royalties | 7,500 | |
| Prime cost | 344,700 | |
| Factory overheads: | ||
| Indirect wages | 42,300 | |
| Rent and rates (3/4 × 32,000) | 24,000 | |
| Power | 19,700 | |
| Insurance (2/3 × 9,600) | 6,400 | |
| Depreciation of machinery (10% × 150,000) | 15,000 | |
| Total factory overheads | 107,400 | |
| 452,100 | ||
| Add opening work in progress | 11,200 | |
| 463,300 | ||
| Less closing work in progress | (13,300) | |
| Cost of production | 450,000 | |
| Manufacturing profit (450,000 × 25%) | 112,500 | |
| Transfer price of finished goods | 562,500 |
Workings: 27,500 + 213,400 = 240,900; − 3,400 = 237,500; + 5,600 = 243,100; − 25,900 = 217,200. Prime cost 217,200 + 120,000 + 7,500 = 344,700. Overheads 42,300 + 24,000 + 19,700 + 6,400 + 15,000 = 107,400. 344,700 + 107,400 = 452,100; + 11,200 = 463,300; − 13,300 = 450,000. Mark-up 450,000 × 25/100 = 112,500; 450,000 + 112,500 = 562,500.
(b) Provision for unrealised profit at 31 March 2026 = 46,800 × 25/125 = 9,360. Provision at 1 April 2025 = 8,160 (check: 40,800 × 25/125 = 8,160). Increase = 9,360 − 8,160 = 1,200.
| Nadia Textiles: Income statement for the year ended 31 March 2026 | $ | $ |
|---|---|---|
| Revenue | 620,000 | |
| Opening inventory of finished goods | 40,800 | |
| Add transfer price of finished goods | 562,500 | |
| 603,300 | ||
| Less closing inventory of finished goods | (46,800) | |
| Cost of sales | (556,500) | |
| Gross profit | 63,500 | |
| Add manufacturing profit | 112,500 | |
| 176,000 | ||
| Less increase in provision for unrealised profit | (1,200) | |
| 174,800 | ||
| Less expenses: | ||
| Office salaries | 58,000 | |
| Rent and rates (1/4 × 32,000) | 8,000 | |
| Insurance (1/3 × 9,600) | 3,200 | |
| Depreciation of office equipment | 2,000 | |
| Distribution costs | 27,900 | |
| Total expenses | (99,100) | |
| Profit for the year | 75,700 |
Workings: 40,800 + 562,500 = 603,300; − 46,800 = 556,500; 620,000 − 556,500 = 63,500; + 112,500 = 176,000; − 1,200 = 174,800. Expenses 58,000 + 8,000 + 3,200 + 2,000 + 27,900 = 99,100. 174,800 − 99,100 = 75,700.
(c) Raw materials 25,900 + work in progress 13,300 + finished goods at cost (46,800 − 9,360 = 37,440) = 76,640. Check: 37,440 × 125/100 = 46,800.
Answer 3
(a) Mark-up 20%, so profit in inventory = transfer value × 20/120. At 1 January 2025: 33,600 × 20/120 = 5,600. At 31 December 2025: 28,800 × 20/120 = 4,800.
(b) The provision has fallen by 5,600 − 4,800 = 800. Journal: Dr Provision for unrealised profit 800; Cr Income statement 800. The decrease is added to profit for the year.
(c) 28,800 − 4,800 = 24,000 (check: 24,000 × 120/100 = 28,800).
(d) The closing finished goods are valued at transfer price, which includes manufacturing profit. That profit has not been realised because the goods have not been sold to a customer. Inventory must be valued at the lower of cost and net realisable value, so the profit element must be removed; the provision reduces the inventory to cost in the statement of financial position and stops profit for the year being overstated.
Answer 4
Any two differences: direct costs can be traced to individual units of product while overheads cannot; direct costs normally vary with output while many overheads are fixed for the period; direct costs make up prime cost while overheads are added after prime cost in the manufacturing account. Examples: direct cost, the wages of a machine operator or the timber used in a chair; factory overhead, the factory supervisor's salary, factory rent or depreciation of machinery.
Answer 5
Opening work in progress is added to the total of prime cost and factory overheads, because those partly made goods were completed during the year, so the cost already spent on them forms part of the cost of goods completed this year. Closing work in progress is deducted, because the cost spent on goods still unfinished at the year end has not produced completed goods and is carried forward to next year. The result is the cost of production of goods actually completed in the year.
Answer 6
(a) Cost of production = 184,000 + 61,000 + 9,500 − 10,000 = 244,500. Workings: 184,000 + 61,000 = 245,000; + 9,500 = 254,500; − 10,000 = 244,500. Cost per unit = 244,500 ÷ 15,000 = $16.30.
(b) On the face of it buying is cheaper: 16.30 − 16.00 = $0.30 per unit, or 15,000 × 0.30 = $4,500 a year. But $38,000 of the overheads is depreciation and rent, which will continue whether or not the factory produces. If the business buys in, the avoidable cost of making is only 244,500 − 38,000 = 206,500, or $13.77 per unit, so buying at $16.00 would make the business worse off by 15,000 × 16.00 − 206,500 = 240,000 − 206,500 = $33,500 a year unless the factory and machinery can be sold or used for something else. Other factors: the supplier's reliability, quality and future prices; redundancy costs and loss of skilled workers; loss of control over production; whether the freed capacity could earn a contribution elsewhere. On the figures given, Kamran should continue to manufacture.
