A Level · Economics 9708 · Market structures: perfect competition, monopoly, monopolistic competition and oligopoly
Market structures: perfect competition, monopoly, monopolistic competition and oligopoly
Opens inside this page. Prefer your own PDF app? Open the PDF.
Check yourself
5 quick questions on A Level Economics
Tap an answer to see if you are right, and why. Free, no sign-up.
Start the free test👍 6 students found these notes useful
Was this note useful?
Full text of Market structures: perfect competition, monopoly, monopolistic competition and oligopoly
Market structure describes how a market is organised: the number of firms, ease of entry, whether products are identical or differentiated and how well informed buyers are. Structure shapes conduct (pricing and output) and so performance (profit, efficiency, what consumers get). This document covers the A2 content of Cambridge 9708 on firms and market structures, with O Level 2281 links at the end. Every diagram is described in words; practise drawing each from memory.
Objectives of firms
Profit maximisation
Profit maximisation is producing the output at which marginal cost equals marginal revenue (MC = MR), with MC rising through MR, so that total revenue exceeds total cost by the largest possible amount.
If MR exceeds MC, the last unit added more to revenue than to cost, so expanding output raises profit. If MC exceeds MR, cutting output raises profit. Only where MC = MR is there no reason to change. It is the standard assumption because a firm that ignores profit for long is bought out or driven out.
Other objectives
- Revenue maximisation (Baumol): produce where MR = 0, where total revenue is highest. Managers rewarded on sales may prefer this. Output is higher and price lower than under profit maximisation.
- Sales (volume) maximisation: produce the highest output that still covers costs, where AR = AC, so the firm earns only normal profit. Often used to build market share or deter entry.
- Satisficing (Simon): managers aim for a profit that keeps shareholders content, then pursue their own goals (status, growth, an easier life). It follows from the divorce of ownership from control in large companies.
- Survival, growth and social objectives: accepting short-run losses in a price war (provided price covers average variable cost), expanding for scale and security from takeover, or paying above the market wage and limiting pollution, at the expense of current profit.
Exam tip. Ranked by output, lowest to highest: profit maximisation (MC = MR), revenue maximisation (MR = 0), sales maximisation (AR = AC). By price the order is reversed. Be ready to show all three on one diagram.
Revenue: total, average and marginal
Definitions
Total revenue (TR) is the total income a firm receives from selling its output: TR = price × quantity sold.
Average revenue (AR) is revenue per unit sold: AR = TR ÷ Q. Since every unit sells at the same price (unless the firm price discriminates), AR equals price and the AR curve is the firm's demand curve.
Marginal revenue (MR) is the change in total revenue from selling one more unit: MR = change in TR ÷ change in Q.
The price taker: AR = MR
In perfect competition the firm is so small relative to the market that it can sell any amount at the market price and nothing above it. Its demand curve is horizontal (perfectly elastic) at that price. Each extra unit sells at the same price, so MR equals price: AR = MR = P, one horizontal line, and TR rises in a straight line through the origin.
The price maker: MR below AR
A firm facing a downward-sloping demand curve (monopoly, monopolistic competition, oligopoly) must lower price to sell more, and the lower price applies to all the units it was already selling. The revenue from one more unit is the new price minus the revenue lost on earlier units, so MR is less than AR at every output after the first.
Rule to learn. For a straight-line AR (demand) curve, the MR curve starts at the same point on the price axis and falls twice as steeply, cutting the quantity axis at half the quantity where AR does. MR is positive where demand is price elastic (PED greater than 1), zero where PED = 1 (total revenue is at its maximum) and negative where demand is price inelastic.
A profit-maximising firm therefore never produces on the inelastic part of its demand curve: there MR is negative while MC is positive, so MC = MR cannot hold.
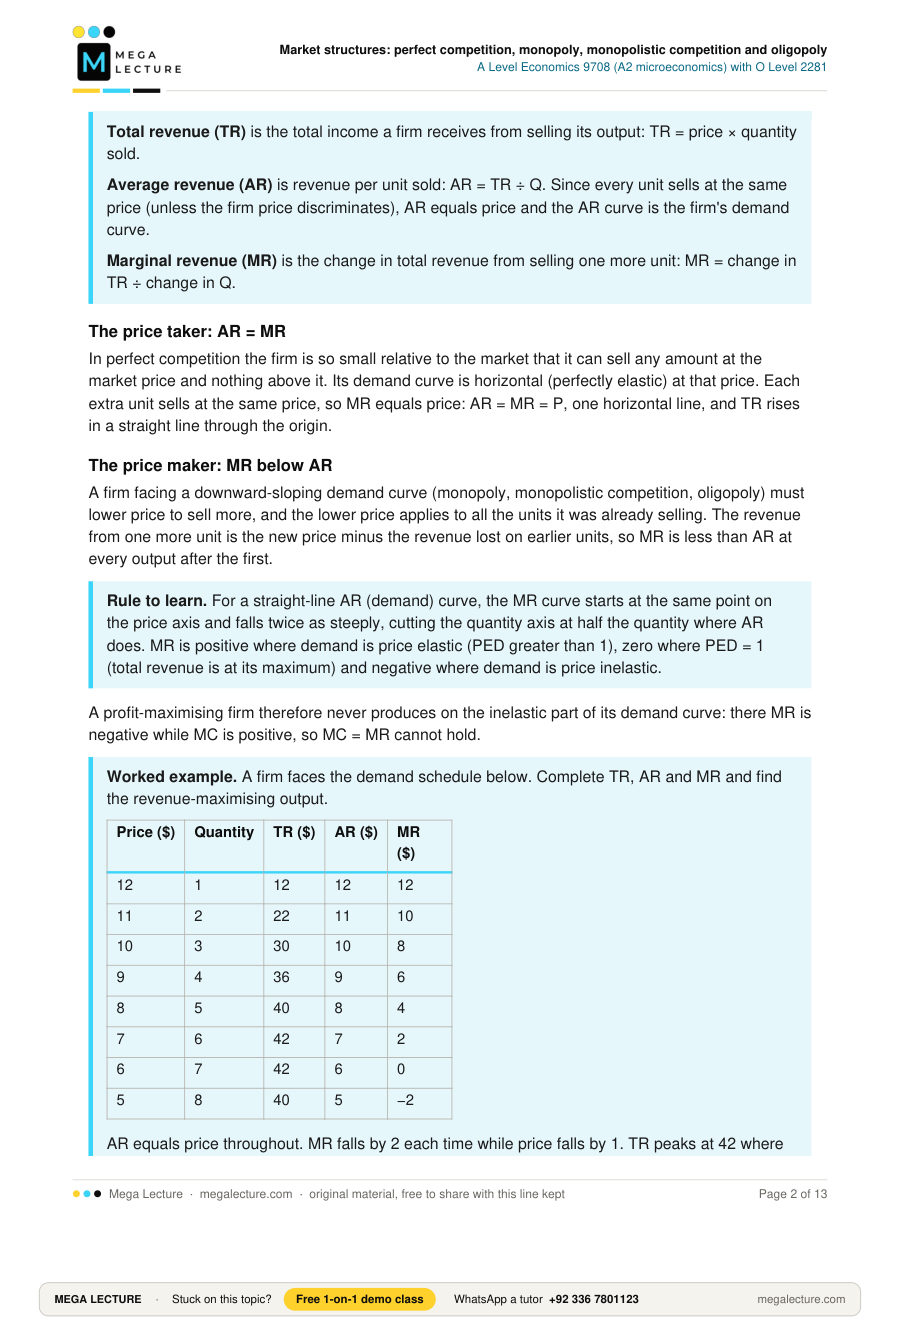
Worked example. A firm faces the demand schedule below. Complete TR, AR and MR and find the revenue-maximising output.
| Price ($) | Quantity | TR ($) | AR ($) | MR ($) |
|---|---|---|---|---|
| 12 | 1 | 12 | 12 | 12 |
| 11 | 2 | 22 | 11 | 10 |
| 10 | 3 | 30 | 10 | 8 |
| 9 | 4 | 36 | 9 | 6 |
| 8 | 5 | 40 | 8 | 4 |
| 7 | 6 | 42 | 7 | 2 |
| 6 | 7 | 42 | 6 | 0 |
| 5 | 8 | 40 | 5 | −2 |
AR equals price throughout. MR falls by 2 each time while price falls by 1. TR peaks at 42 where MR reaches 0 (the 7th unit); beyond that MR is negative and TR falls.
Profit and the shut-down rule
Normal profit is the minimum return needed to keep the entrepreneur and capital in their present use. It is counted as a cost, so it is included in average cost (AC). A firm earning normal profit has AR = AC and economic profit of zero.
Supernormal (abnormal) profit is any profit above normal profit, earned when AR is greater than AC. Total supernormal profit = (AR − AC) × Q.
Shut-down rule. In the short run a firm keeps producing as long as AR ≥ AVC, because fixed costs must be paid anyway and any revenue above variable cost reduces the loss. In the long run all costs are variable, so it needs AR ≥ AC to stay.
Perfect competition
Assumptions
- Many buyers and many sellers, each too small to affect the market price (firms are price takers).
- Homogeneous (identical) products, so buyers have no reason to prefer one seller.
- Perfect knowledge: all buyers and sellers know prices and technology.
- No barriers to entry or exit in the long run.
- Factors of production are perfectly mobile.
No real market meets all of these; the model is the benchmark against which the others are judged.
Short-run equilibrium
Draw two diagrams side by side. Left, the industry: market demand and supply fix price P. Right, the firm: a horizontal line at P labelled AR = MR = D, U-shaped AC and AVC, and an MC curve cutting both at their lowest points. The firm produces q where MC = MR. Its profit depends on where AC lies at q:
- AC below P: supernormal profit, the rectangle between P and AC across q units.
- AC equal to P: normal profit only.
- AC above P but AVC below P: a loss, but the firm keeps producing in the short run.
- P below AVC: the firm shuts down.
Since the firm always produces where P = MC (provided P ≥ AVC), its short-run supply curve is its MC curve above minimum AVC.
Long-run equilibrium
Supernormal profit attracts new firms: there are no barriers and perfect knowledge means the profit is seen. Entry shifts industry supply right, price falls and each firm's AR = MR line moves down, until price reaches minimum AC and only normal profit remains. Losses work in reverse: firms leave, supply shifts left and price rises until the survivors cover AC. In long-run equilibrium P = AR = MR = MC = minimum AC.
Definition to learn. In long-run equilibrium under perfect competition, each firm produces at the minimum point of its average cost curve and earns normal profit only, with price equal to both marginal cost and average cost.
Efficiency
In the long run perfect competition is productively efficient (output at minimum AC) and allocatively efficient (P = MC: the value consumers place on the last unit equals its resource cost). It is the only structure that achieves both without regulation. It is weak on dynamic efficiency: no supernormal profit to fund research, and any innovation is copied at once.
Monopoly
Characteristics
A pure monopoly is a market with a single seller of a product that has no close substitutes, protected by high barriers to entry. Competition law often treats a firm as having monopoly power at a much lower share, such as 25%.
The monopolist is the industry, so its AR curve is the downward-sloping market demand curve, with MR below it. It is a price maker, but it cannot choose both price and quantity: fixing one fixes the other.
Equilibrium in the short run and the long run
Draw a downward-sloping AR with MR below it, falling twice as steeply, plus U-shaped AC and MC. The monopolist produces Qm where MC = MR and reads up to AR to set price Pm. AC at Qm lies below Pm, so there is supernormal profit, the rectangle between Pm and AC over Qm units. Entry is blocked, so nothing erodes this profit: the long-run equilibrium is the same as the short-run one.
Three features distinguish monopoly from perfect competition. Price is above marginal cost, because price is read from AR, which lies above MR. Output is not at minimum AC. And the monopolist has no supply curve: the quantity chosen depends on the position and slope of demand, not just on price.
Natural monopoly
A natural monopoly exists where economies of scale are so large relative to market demand that long-run average cost is still falling at the output that satisfies the whole market, so one firm can supply the market at lower average cost than two or more could.
Water pipes, electricity grids and railway track are the usual examples: duplicating the network doubles fixed cost for no gain. LRAC falls across the whole range of demand with LRMC below it, so pricing at MC would mean a loss; regulators often set price equal to AC or subsidise marginal cost pricing.
Case for and against monopoly
| Against monopoly | For monopoly |
|---|---|
| Higher price and lower output than perfect competition, with a deadweight loss of surplus | Economies of scale can give a lower AC and even a lower price than many small competitive plants |
| Allocative inefficiency (P > MC) and productive inefficiency (not at minimum AC) | Supernormal profit funds research and development, giving dynamic efficiency |
| X-inefficiency: without competition, costs drift upwards | Patents reward innovation that would otherwise not happen |
| Less choice and less pressure to improve quality | Natural monopolies avoid wasteful duplication of networks |
| Redistribution from consumers to shareholders | Price discrimination can make otherwise unviable services viable |
Monopolistic competition
Characteristics
Monopolistic competition is a market with many firms selling differentiated products, each with a small share of the market, and with low barriers to entry and exit.
Hairdressers, restaurants and small clothing brands fit this structure. Differentiation (branding, location, quality, service) gives each firm a little monopoly power, so its demand curve slopes down, but the many close substitutes make it highly elastic.
Short-run equilibrium
The diagram is a monopoly diagram with a flatter AR. The firm produces where MC = MR and sets price from AR; if AR is above AC at that output it earns supernormal profit.
Long-run equilibrium
Easy entry means supernormal profit attracts new firms with their own varieties. Each existing firm loses customers, so its AR shifts left and becomes more elastic. Entry continues until AR is just tangent to AC: at the profit-maximising output (still MC = MR) price equals average cost and only normal profit remains. In the diagram AR touches AC from below at the chosen output, where AC is still falling. This is the tangency equilibrium.
Definition to learn. In the long run under monopolistic competition the firm earns normal profit only, producing where MC = MR and where AR is tangent to AC, on the falling part of the AC curve.
Efficiency
The firm is not productively efficient: it produces left of minimum AC, with excess capacity. It is not allocatively efficient: P > MC. Against this, consumers gain variety, and the inefficiency is small because demand is elastic. Advertising costs may be wasteful or may provide useful information, a point to argue both ways.
Oligopoly
Characteristics
Oligopoly is a market dominated by a few large firms, each with a significant market share, protected by substantial barriers to entry. Products may be homogeneous (steel, cement) or differentiated (cars, mobile networks). The defining feature is interdependence: each firm's decisions depend on how it expects rivals to react.
A concentration ratio is the share of the market held by the largest firms: a five-firm ratio of 80% means the five largest firms sell 80% of industry output.
The kinked demand curve and price rigidity
The kinked demand model explains why oligopoly prices often stay stable even when costs change. Each firm believes that if it raises price, rivals will not follow (it loses many customers: demand is elastic above the current price), but if it cuts price, rivals match the cut (it gains few customers: demand is inelastic below the current price).
Draw the AR curve with a kink at the current price P and output Q: flat above the kink, steep below. The MR curve follows each section separately, so it has a vertical gap directly below the kink. Draw MC passing through this gap. Any shift of MC that stays within the gap leaves MC = MR satisfied at Q, so output and price do not change.
Evaluation of the kinked demand curve. It explains why a price is stable but not how it was set. Rivals do not always react asymmetrically: price rises are often followed when all firms face the same cost increase. It cannot explain price wars.
Collusion
Collusion is an agreement, open or tacit, between firms to limit competition, typically by fixing prices, restricting output or sharing the market, in order to earn profits closer to the monopoly level.
A cartel is a formal collusive agreement in which firms act together as if they were a single monopolist, setting the industry output where industry MC = MR and dividing that output between members by quota. Cartels are illegal in most countries; OPEC survives because its members are governments.
Under price leadership one firm (the dominant, lowest-cost or barometric firm) sets price and the rest follow. Tacit collusion is reaching the same prices without any agreement, for example by shared cost-plus pricing or by avoiding anything that would start a price war.
Collusion is most likely with few firms, similar products and costs, stable demand, hard entry and output that is easy to monitor. Cartels break down because each member gains by cheating, selling above its quota at just under the cartel price; once one cheats, others follow. Entrants, falling demand and legal action also undermine them.
Game theory: the prisoner's dilemma
Two firms, A and B, each choose a high or a low price; the table shows annual profit in millions of dollars.
| B sets high price | B sets low price | |
|---|---|---|
| A sets high price | A 10, B 10 | A 2, B 14 |
| A sets low price | A 14, B 2 | A 5, B 5 |
Whatever B does, A earns more with a low price (14 rather than 10 if B is high; 5 rather than 2 if B is low). Low price is A's dominant strategy, and by symmetry B's too. Both end at low price with 5 each, though both would prefer 10 each: the Nash equilibrium, where neither firm can gain by changing its own choice alone. The dilemma shows why collusion is attractive (10, 10) and why it is unstable (each can gain by cheating). Repeated interaction and the threat of retaliation can sustain the high-price outcome, which is how tacit collusion works. Because price cuts are so easily matched, oligopolists prefer non-price competition: advertising, design, quality and service.
Barriers to entry
A barrier to entry is anything that makes it difficult or costly for a new firm to enter a market and compete with existing firms, allowing incumbents to keep supernormal profit in the long run.
| Type | Examples |
|---|---|
| Legal barriers | Patents and copyright; licences and franchises; tariffs and quotas against foreign entrants; state ownership |
| Economies of scale and high fixed costs | An entrant starting small has a much higher average cost than the incumbent; in a natural monopoly this alone blocks entry |
| Sunk costs | Costs that cannot be recovered on exit (advertising, specialised equipment, research), which make entry risky |
| Control of essential inputs or outlets | Ownership of the only raw material source, the pipeline, the airport slots or the shelf space |
| Brand loyalty, network effects and switching costs | Heavy advertising creates loyal customers and raises the cost of being noticed; a product that is more valuable the more people use it (social media, payment systems) and costs of switching lock customers in |
| Strategic (deliberate) barriers | Limit pricing (a price below the profit-maximising level so that entry looks unprofitable), predatory pricing (pricing below cost to drive an entrant out, illegal in most places), spare capacity held as a threat, product proliferation that fills every niche |
Barriers to exit also matter: if leaving is costly (long leases, redundancy payments, unsaleable assets) firms are reluctant to enter at all.
Price discrimination
Price discrimination is charging different prices to different consumers, or groups of consumers, for the same product, where the price difference is not explained by a difference in the cost of supply.
Three conditions are necessary: the firm must have some price-setting power (a downward-sloping demand curve); it must be able to separate the market into groups with different price elasticities of demand (by age, time, location or income); and it must be able to prevent resale from the low-price group to the high-price group.
Degrees of price discrimination
- First degree: each unit sold at the maximum the buyer will pay, so the firm takes all the consumer surplus and MR becomes the demand curve. Rare; haggling in a bazaar comes closest.
- Second degree: price varies with quantity bought or version chosen: bulk discounts, off-peak tariffs, economy and business class. Consumers sort themselves.
- Third degree: consumers are grouped by an observable feature and each group charged its own price: student fares, matinee prices, cheaper software in lower-income countries. This is the version drawn in exams.
Third-degree diagram in words
Draw three panels. Panel A: the inelastic market (business travellers), steep AR with MR below. Panel B: the elastic market (leisure travellers), flatter AR with MR below. Panel C: the whole firm, the horizontal sum of the two MR curves with the firm's MC. Find the output where MC = combined MR in panel C and read that MR level across to A and B: in each sub-market the firm sells where its MR equals the common level and charges the price on that sub-market's AR. The inelastic market pays more. The rule is MRA = MRB = MC.
Worked example. A cinema has a marginal cost of $2 per seat and empty seats. Adult demand is relatively inelastic: at $10 it sells 100 adult tickets a day, with MR on the last ticket $2. Student demand is relatively elastic: at $6 it sells 80 student tickets, also with MR $2. Compare with a single price of $8, at which it sells 120 tickets.
With discrimination: revenue = 100 × $10 + 80 × $6 = $1000 + $480 = $1480; variable cost = 180 × $2 = $360; contribution to profit = $1120.
With a single price: revenue = 120 × $8 = $960; variable cost = 120 × $2 = $240; contribution = $720.
Discrimination raises profit by $400 and fills 60 more seats, mostly for students who would not pay $8. The firm and the students gain; the adults lose.
Effects of price discrimination
The firm converts consumer surplus into profit. Consumers in the inelastic market pay more; those in the elastic market pay less, and some who were priced out can now buy. Total output is usually higher, and the extra revenue can make an otherwise unviable service run (a rural bus route, a drug sold cheaply in poor countries). Against this, it can fund predatory pricing, and separating markets costs money.
Contestable markets
A contestable market is one in which entry and exit are free and costless, in particular with no sunk costs, so that the threat of entry alone forces existing firms to behave competitively whatever the number of firms actually in the market.
The theory (Baumol again) separates the number of firms from their behaviour. Even a single firm in a perfectly contestable market earns only normal profit, because supernormal profit would attract "hit and run" entry: a rival enters, takes the profit while it lasts and leaves at no cost when the incumbent responds. To forestall this the incumbent prices at average cost and keeps costs down. Contestability needs low sunk costs, no legal barriers, access to the same technology and little brand loyalty.
A regulator can therefore make a monopolised market more contestable instead of breaking the firm up: remove legal barriers, force a network owner to lease it to rivals at a fair price (telecoms, rail track), shorten franchises. Airlines became more contestable when planes could be leased and routes were deregulated.
Evaluation. Perfectly contestable markets are as rare as perfectly competitive ones; most entry involves some sunk cost, such as advertising. Incumbents can reduce contestability deliberately through branding, loyalty schemes and limit pricing. Still, the idea that potential competition matters as much as actual competition has shaped competition policy.
Efficiency in each structure
Allocative efficiency is achieved when resources are allocated to produce the combination of goods that consumers value most, which occurs where price equals marginal cost (P = MC) in every market.
Productive efficiency is achieved when output is produced at the lowest possible average cost, at the minimum point of the AC curve, so no resources are wasted.
Dynamic efficiency is improvement over time in products and processes through investment, research and innovation, lowering costs or raising quality in the long run.
X-inefficiency is the rise in average cost above the minimum possible that occurs when a firm faces little competition and so has weak incentives to control costs.
| Structure | Long-run profit | Allocative (P = MC)? | Productive (min AC)? | Dynamic |
|---|---|---|---|---|
| Perfect competition | Normal | Yes | Yes | Weak: no funds, innovations copied |
| Monopolistic competition | Normal | No, P > MC by a small margin | No, excess capacity | Limited: little profit; some product innovation |
| Oligopoly | Supernormal | No | Usually no, though large firms gain economies of scale | Often strong: profit funds R&D and rivalry drives innovation |
| Monopoly | Supernormal | No, P well above MC | No, plus X-inefficiency | Possible: profit and patents fund research, but no pressure to use it |
The table is the starting point for comparison essays, not the end. A monopoly with large economies of scale may have lower AC and even a lower price than a competitive industry; an oligopoly with strong non-price competition may give consumers better products than perfect competition could; a contestable monopoly may behave almost as if it were competitive.
Evaluation points for 20-mark essays
A top answer defines terms, draws and explains the relevant diagram, applies it to the question, then evaluates: weighing arguments, not listing more of them.
- Assumptions versus reality. Perfect competition and pure monopoly are extreme models; most real markets are oligopolies or monopolistically competitive. Judge a conclusion by how far the assumptions hold in the market named.
- Static versus dynamic. Perfect competition wins on static efficiency, but the supernormal profit of monopoly and oligopoly can fund innovation that lowers costs for everyone.
- Economies of scale and contestability. The claim that monopoly means higher prices assumes identical cost curves; where minimum efficient scale is large, many small firms would have higher average cost. And the threat of entry matters as much as the number of firms: a contestable monopoly may price near average cost.
- Objectives and regulation. The textbook results assume profit maximisation. A sales-maximising or satisficing monopolist sets a lower price and higher output; a state-owned monopoly may price at MC; price caps and competition law change the outcome. Conduct cannot be judged from structure alone.
- Short run versus long run. Supernormal profit in monopolistic competition is temporary; in monopoly it lasts only while the barriers hold, and technology (streaming against cinemas, mobile against fixed-line) often dissolves them.
- Whose interest? Say whose welfare you are judging. Price discrimination hurts one group of consumers, helps another and helps the firm.
- Local context. Pakistan's cement and sugar sectors have faced cartel findings; telecoms moved from a state monopoly to an oligopoly with much lower prices; a regional electricity distributor illustrates natural monopoly. Use such examples briefly and only where they fit.
Exam tip. Finish with a justified judgement. "It depends on..." is a valid conclusion if you say what it depends on (the size of economies of scale, how contestable the market is, whether profit is reinvested). Never end with a summary of what you have already written.
Links to O Level Economics 2281
O Level asks you to distinguish competitive markets from monopoly, describe each and discuss their advantages and disadvantages, without MC = MR diagrams. The tables above on the case for and against monopoly, barriers to entry and efficiency are directly usable in 2281 answers, in words rather than curves, as are the objectives of firms. Moving from 2281 to 9708, the new material is the revenue curves, the MC = MR rule, the equilibrium diagrams, price discrimination, the kinked demand curve and the formal efficiency definitions.
Quick check
- Explain why the marginal revenue curve of a monopolist lies below its average revenue curve. [4]
- A firm's demand curve is a straight line: at a price of $20 it sells nothing, at $0 it would sell 100 units. (a) State the output at which MR = 0. (b) State the range of output over which demand is price inelastic. (c) Explain why a profit-maximising firm would never choose an output in that range. [6]
- Explain, with reference to a diagram you describe, how a perfectly competitive firm earning supernormal profit in the short run comes to earn only normal profit in the long run. [8]
- Using the kinked demand curve model, explain why prices in an oligopoly may remain unchanged when a firm's costs rise. [6]
- Explain why a firm that is the only seller in a contestable market may still earn only normal profit. [6]
- Compare the allocative and productive efficiency of a monopoly with that of a perfectly competitive industry in long-run equilibrium. [8]
- Explain why a firm in monopolistic competition operates with excess capacity in the long run. [6]
- Explain why cartels tend to be unstable. [6]
- A publisher sells a textbook in two markets. In the home market demand is relatively inelastic and the profit-maximising price is $40 for 2000 copies. In the export market demand is relatively elastic and the profit-maximising price is $25 for 3000 copies. Marginal cost is constant at $10 per copy. (a) Calculate the total contribution to profit (revenue minus variable cost) from the two markets. (b) Calculate the contribution if the publisher charged $40 everywhere and sold only 2000 copies in total, and comment on the result. [6]
- "Monopoly always operates against the interest of consumers." Evaluate this statement. [20]
1. A monopolist faces the downward-sloping market demand curve, its AR curve, so to sell an extra unit it must cut price, and the cut applies to every unit sold. The marginal revenue from the extra unit is its price minus the revenue lost on all earlier units now sold at the lower price. Since something is always subtracted, MR is below price (AR) at every output after the first. For a straight-line AR, MR falls twice as steeply and reaches zero at half the output where AR does.
2. (a) With a straight-line demand curve MR cuts the quantity axis at half the quantity intercept, so MR = 0 at 50 units. (b) Demand is inelastic below the midpoint of the demand curve, from 50 to 100 units. (c) Over that range MR is negative: each extra unit cuts total revenue while adding to cost, so MC = MR cannot hold. Reducing output would raise revenue and lower cost at once, so a profit maximiser always operates on the elastic part of demand.
3. Describe the industry diagram, where market demand and supply set price P1, and the firm diagram with a horizontal AR = MR line at P1 and U-shaped AC and MC. The firm produces q1 where MC = MR; AC at q1 is below P1, so it earns supernormal profit, the rectangle between P1 and AC. With no barriers and perfect knowledge, new firms enter. Industry supply shifts right, price falls, the firm's AR = MR line moves down and its profit rectangle shrinks. Entry stops when price reaches P2 at minimum AC: AR = AC, only normal profit, no incentive to enter, and P = MC = minimum AC.
4. In the kinked demand model each firm assumes rivals will not follow a price rise but will match a price cut. Demand is therefore elastic above the current price (a rise loses many customers) and inelastic below it (a cut gains few, because rivals cut too). This gives a kink in AR at the current price and a vertical gap in MR directly below it, through which MC passes. If costs rise, MC shifts up, but while it stays within the gap it still meets MR at the same output, so price is unchanged. Firms absorb the cost rise in lower profit rather than risk losing sales, which explains the price rigidity seen in many oligopolies.
5. In a contestable market entry and exit are free, with no sunk costs. If the sole firm priced above average cost, an entrant could come in, undercut it, take the profit and leave costlessly if the incumbent retaliated: hit and run entry. Knowing this, the incumbent prices at the level that earns only normal profit and keeps costs down, leaving no profitable opening. The threat of competition does the work that actual competition does in perfect competition. This depends on sunk costs really being low; where advertising or specialised assets are needed to enter, the incumbent regains some freedom to raise price.
6. In long-run equilibrium a perfectly competitive firm produces where P = MC, so it is allocatively efficient: the value consumers place on the last unit equals its resource cost. It also produces at minimum AC, so it is productively efficient. A monopolist produces where MC = MR and prices from AR, above MR, so P > MC: output is below the allocatively efficient level and there is a deadweight loss. Its output is left of minimum AC, so it is productively inefficient, and weak competition may add X-inefficiency. The comparison assumes the same cost curves; with economies of scale the monopolist's AC may be lower than any competitive firm could reach, and its profit may fund dynamic efficiency.
7. Low barriers mean supernormal profit attracts entry, which shifts each firm's AR left until it is just tangent to AC and only normal profit remains. Because the product is differentiated, AR still slopes down, and a downward-sloping line can only touch a U-shaped AC curve on its falling part, left of the minimum. The firm therefore produces below the output that would minimise AC: it has excess capacity, since it could lower average cost by producing more, but the extra units could only be sold below cost. The result is productive inefficiency, offset by the variety consumers enjoy.
8. A cartel sets output where industry MC = MR and allocates quotas, so price is above marginal cost for every member. That gap is the problem: each member can raise its own profit by selling above its quota at slightly below the cartel price, since each extra unit still earns more than it costs. If one cheats it gains at the others' expense; if all cheat, output rises and price falls towards the competitive level, the prisoner's dilemma. Detection is hard with many members or secret discounts. Cartels are further weakened by entrants attracted by the high price, by falling demand that makes quotas painful, by cost differences between members, and by competition law which makes agreements unenforceable.
9. (a) Home market: revenue 2000 × $40 = $80 000, variable cost 2000 × $10 = $20 000, contribution $60 000. Export market: revenue 3000 × $25 = $75 000, variable cost 3000 × $10 = $30 000, contribution $45 000. Total contribution = $105 000. (b) Single price of $40: revenue $80 000, variable cost $20 000, contribution $60 000. Discrimination adds $45 000 to profit and sells 3000 more copies, all to export buyers who would not pay $40; home buyers are no worse off. It works only if the publisher can stop export copies being shipped back to the home market.
10. Plan for a full answer. Define monopoly (single seller, no close substitutes, high barriers) and consumer interest (low prices, high output, choice, quality, improvement over time). Describe the standard diagram: output where MC = MR, price from AR, supernormal profit, P above MC, output below minimum AC. Case for the statement: higher price and lower output than perfect competition, deadweight loss, allocative and productive inefficiency, possible X-inefficiency, less choice. Case against: economies of scale may give a lower AC and price than many small firms could manage, especially in a natural monopoly; supernormal profit can fund research and so dynamic efficiency; price discrimination can serve consumers who would otherwise be priced out; a contestable monopoly must price near average cost; a sales-maximising, satisficing or regulated monopoly does not behave as the diagram predicts. Evaluate: "always" is the weak point, because the outcome depends on cost conditions, contestability, what the firm does with its profit and whether regulation works. Judgement: monopoly often works against consumers on price, but where economies of scale are large or innovation matters they can be better off than under competition, so the statement is too strong and the right policy is regulation of conduct, not a blanket ban.
